The Help to Buy Scheme Explained
The Help to Buy scheme explained in plain terms: how the equity loan worked, who qualified, the application steps and what repaying it means when you sell.
The Help to Buy scheme explained
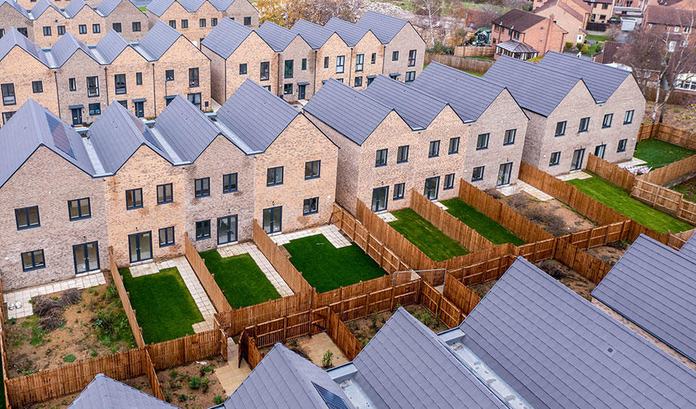
The Help to Buy scheme, introduced by the UK government in 2013, aimed to assist first-time buyers and existing homeowners in purchasing new-build properties. With rising property prices, particularly in urban areas, the scheme became a common route for those struggling to gather a large enough deposit. This article sets out the Help to Buy scheme explained in plain terms: how it worked, its benefits, its limitations, and the rules that still matter to anyone who bought a home under it.
Worth saying at the outset: the scheme is now closed to new applications. If you are searching for "help to buy" or "helptobuy" hoping to apply, that door has shut. What follows still matters, though, because the equity loan rules continue to apply to every home bought under the scheme.
Overview of the Help to Buy scheme
Help to Buy was essentially a government-backed equity loan that helped buyers purchase new-build homes. Initially the scheme supported both new-build and existing properties, but it was later refined to focus exclusively on new-builds. Under the scheme, buyers needed to provide a minimum deposit of 5% of the property's value. The government then offered an equity loan of up to 20% (40% in London) of the property's value, which was interest-free for the first five years. This allowed buyers to secure a mortgage for the remaining 75% (55% in London).
How does the Help to Buy scheme work
The key point people miss is that the equity loan is a percentage of the property's value, not a fixed cash sum. If you borrowed 20% of the value, you owe 20% of whatever the property is worth when you come to repay or sell. That works in your favour if prices fall and against you if they rise. It is the single most important thing to understand about the scheme.
Benefits of the Help to Buy scheme
One of the most significant advantages was the reduced deposit requirement, which lowered the initial financial barrier for buyers. This was particularly useful for first-time buyers trying to save for a large deposit while also paying rent. By enabling buyers to secure a smaller mortgage against the property's value, the scheme often gave access to better interest rates, making monthly repayments more manageable.
The interest-free period on the equity loan for the first five years also gave buyers breathing space to manage their finances and build equity. That could be especially helpful for young professionals and families trying to establish themselves without immediate financial strain.
Limitations and considerations
Help to Buy explained honestly means covering the drawbacks as well. The equity loan is not free money. After the initial five-year interest-free period, buyers must begin paying interest on the loan, which started at 1.75% and increased annually by the Consumer Price Index (CPI) plus 2%. This adds to the monthly commitment over time and needs to sit in any long-term financial plan.
Another limitation was the restriction to new-build properties. While this supported the construction industry, it narrowed buyers' choices and ruled out older, characterful homes. New-builds also often carry a premium price, which can offset some of the financial benefit of the scheme.
Changes to the scheme over its lifetime
Over the years the scheme was refined. One significant change, introduced in April 2021, was the implementation of regional price caps. These caps varied across the UK to keep the support aligned with local property markets. For example, the cap was set at typically £600,000 in London, while in the North East it was typically £186,100.
April 2021 also restricted the scheme to first-time buyers only. This shift prioritised those entering the property market for the first time. Existing homeowners had to explore alternatives such as shared ownership or a traditional mortgage.
For a comprehensive assessment of your property's value, consider our RICS Valuation Service.
The Help to Buy application process
Applying for the Help to Buy scheme involved several steps, beginning with selecting a registered Help to Buy home. Buyers researched developers and properties that qualified for the scheme in their chosen area. Once a suitable property was found, they reserved it with the developer and completed a Property Information Form, which was then submitted to the Help to Buy agent in their region.
The Help to Buy agent assessed the application and, if approved, issued an Authority to Proceed (ATP). This document was needed to secure a mortgage and finalise the purchase. Buyers then arranged their mortgage and instructed a solicitor to handle the legal side. It was essential that the mortgage lender was aware of the Help to Buy equity loan, as this could influence the mortgage offer.
Once the mortgage offer was in place and the legal work complete, the buyer and developer set a date for completion. At this point the Help to Buy agent issued an Authority to Exchange (ATE), allowing contracts to be exchanged and the sale to proceed.
Repaying or redeeming the loan
While the scheme provided short-term benefits, the long-term implications matter more once you own the home. Repaying the equity loan is the part to plan for, particularly as interest applies after year five. Buyers can repay the loan in full or in part at any time, with the amount based on the property's current market value. If the property has risen in value, you owe more; if it has fallen, you owe less.
When selling a Help to Buy home, the loan must be repaid from the sale proceeds. To repay or redeem the loan you will need an independent RICS valuation, which the administrator requires to set the figure. We produce these regularly. See How to Navigate the Sale of Your Help to Buy Home and What is the Redemption Process in Help to Buy? for the detail.
If you are weighing up whether the scheme suited you, our guide to the Pros and Cons of the Help to Buy Scheme sets both sides out clearly.
In short, Help to Buy gave many first-time buyers a route into the market by reducing the deposit hurdle and offering favourable terms. But the equity loan is a long-term commitment tied to your property's value, and the rules around repayment and sale need to be understood in full before you act.
Frequently asked questions
What is the government Help to Buy scheme?
It was a government-backed equity loan that helped buyers purchase a new-build home. You put down a 5% deposit, borrowed up to 20% of the value (40% in London) from the government interest-free for five years, and took a mortgage for the rest. The scheme is now closed to new applications.
How does the Help to Buy scheme work when I sell?
The equity loan is repaid from your sale proceeds as a percentage of the sale price, not the amount you originally borrowed. If you borrowed 20% of the value, you repay 20% of what the property sells for. You will need an independent RICS valuation to set the redemption figure.
Can I still make a Help to Buy application?
No. The scheme is closed to new applications. The information here is for buyers who already own a Help to Buy home and need to understand repayment, redemption and selling, and for anyone researching how the scheme worked.
Do I need a valuation to repay my Help to Buy loan?
Yes. The loan administrator requires an independent RICS valuation of your home before you repay or redeem the equity loan. The figure it produces sets how much you owe, so it needs to be accurate and defensible.
What happens after the five-year interest-free period?
Interest becomes payable on the equity loan. It started at 1.75% of the loan and increased each year in line with CPI plus 2%. This is a monthly fee on top of your mortgage, so many owners plan to repay the loan before or around this point.
More on help to buy valuations
What are the Pros and Cons of the Help to Buy Scheme?
The pros and cons of Help to Buy, from lower deposits and equity loans to the risk of negative equity and why the repayment matters.
Read →What is the Redemption Process in Help to Buy?
The Help to Buy scheme, introduced in the UK, has emerged as a significant avenue for numerous individuals desiring to make their way onto the property ladder.
Read →Help to Buy Valuation Cost
What a RICS Help to Buy valuation costs, what affects the price, and why an independent RICS surveyor is required before you repay or sell.
Read →Need a survey on a specific property?
Tell us the address and we will send a fixed price in writing, with no obligation.
Get your fixed quote →