Who organises a survey when buying a house
Wondering who organises a survey when buying a house? A RICS surveyor explains it is the buyer's job, not the agent's or lender's, plus when to book and which level to choose.
5 minute read
If you're buying a home for the first time, the process can feel like a relay of solicitors, agents, mortgage lenders and surveyors, with no one quite telling you who does what. One question comes up again and again: who organises a survey when buying a house?
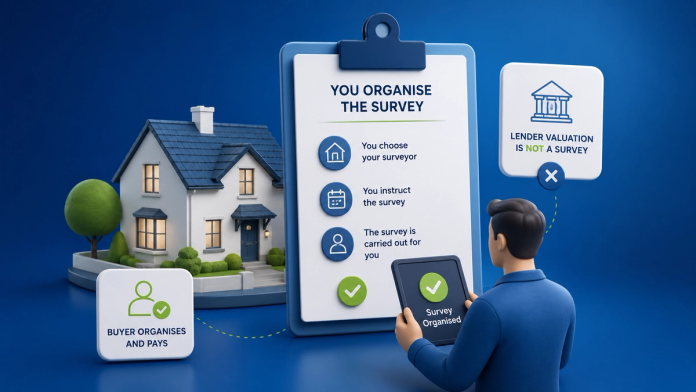
The short answer is that you do. As the buyer, arranging a survey is your responsibility, and it sits separately from anything your mortgage lender or estate agent handles. Understanding who organises a survey when buying a house helps you avoid the common and costly assumption that someone else has it covered. The government's own home-buying guidance treats a survey as something buyers commission for their own protection, rather than a step built into the conveyancing process. You can read the official overview on GOV.UK.
In this article:
- Why the buyer, not the lender or agent, arranges the survey
- How a survey differs from a mortgage valuation
- The right point in the process to book one
- What to look for when choosing a surveyor
"Doesn't the bank already check the house?"
This is the single most common misunderstanding among first-time buyers. When you apply for a mortgage, the lender usually carries out a valuation. It is easy to assume this doubles as a survey. It does not.
A mortgage valuation exists to reassure the lender that the property is worth roughly what they are lending against it. It is brief, often a drive-by or a short visit, and the report is written for the lender rather than for you. It will not tell you about damp in the back bedroom, a sagging roof or movement in a bay window. Those are exactly the things a survey is designed to find.
If you want the difference set out in full, our guide on survey vs mortgage valuation explains what each one covers and why one does not replace the other.
Who organises a survey when buying a house, step by step
In a standard purchase the responsibilities split fairly cleanly. Knowing who handles what removes a lot of the confusion.
1. The estate agent
The agent acts for the seller, not for you. They will not arrange a survey on your behalf, and you should be cautious about accepting a surveyor an agent recommends without checking them independently. There is nothing wrong with a recommendation, but the choice is yours to make.
2. The mortgage lender
The lender instructs the mortgage valuation. Some lenders offer survey products alongside the mortgage, sometimes at a discount. These can be convenient, though they are not always the most thorough option, and you are never obliged to use them.
3. The conveyancer or solicitor
Your solicitor handles the legal side: searches, contracts and the title. They do not commission the survey, although a good one will ask whether you are having one done and may flag issues in the legal documents that a surveyor should look at.
4. You, the buyer
You choose the surveyor, choose the level of survey, book it directly and receive the report. This is the part that catches people out, because nobody in the chain is responsible for prompting you to do it.
| Who | What they arrange | Acts in whose interest |
|---|---|---|
| Estate agent | Viewings, offer negotiation | The seller |
| Mortgage lender | Mortgage valuation | The lender |
| Conveyancer | Legal searches, contracts | You (legal matters) |
| You, the buyer | The survey | You (condition of the property) |
What this means for you:
A mortgage valuation protects the lender. A survey protects you. They are two different things, paid for separately, and one does not replace the other. If you want to understand the property's actual condition, you need to arrange your own survey.
Once you've decided to go ahead, the next choice is which level of survey fits the property. For most conventional homes in reasonable condition, a RICS Home Survey Level 2 is the sensible option. For older, larger or altered buildings, a RICS Home Survey Level 3 gives the deeper investigation those properties usually warrant. Both report condition using a simple rating scale of CR1, CR2 and CR3, where CR3 means a defect is serious or urgent and needs attention.
What buyers tend to miss in practice
In day-to-day experience, the gap is rarely that buyers don't want a survey. It is that nobody tells them the job is theirs, and they have no idea where to start looking for a firm. The moment it lands is often when the solicitor asks the question, and by then the temptation is to rush.
"Most buyers don't realise the survey falls to them. The solicitor asks if they're having one done, and that's often the first they've heard of it. Then they panic and ring round for the cheapest option. The trouble is a mortgage valuation doesn't check thoroughly for things like damp, so they move in and find the problems for themselves. Booking your own survey early, with a firm you've chosen properly, is what saves you that.": Chris Bloor MRICS
Not sure which survey you need?
Tell us about the property and we'll recommend the right level, with no pressure and a clear quote.
What to do next
The usual point to arrange a survey is after your offer has been accepted but before you exchange contracts. That window is the one moment when you have a price agreed and still have room to renegotiate or withdraw if the survey uncovers something significant. A few days after your offer is accepted is the right time to start, rather than waiting for your solicitor to prompt you. For how exchange and completion then follow on, see our guide to exchange and completion.
Choose a RICS-regulated firm, pick the survey level that genuinely fits the property, and book directly so the report is written for you. If you'd like a fuller picture of how the different surveys compare before you choose, our RICS Home Survey guide walks through each level in plain terms.
The take
When you buy a house, organising the survey is your job, not the lender's, the agent's or the solicitor's. The mortgage valuation only protects the bank and won't flag problems like damp. Book your own survey shortly after your offer is accepted, choosing a RICS-regulated firm and the level that suits the property. Doing it early and properly, rather than in a last-minute rush, is what protects your money and your peace of mind.
Frequently asked questions
Who organises a survey when buying a house?
The buyer organises the survey. It is not arranged by the estate agent, the mortgage lender or the solicitor. You choose the surveyor, choose the level of survey, book it directly and receive the report. Nobody else in the chain is responsible for prompting you, so it pays to plan for it yourself.
Does the mortgage valuation count as a survey?
No. A mortgage valuation is carried out for the lender to check the property is worth roughly what they are lending. It is brief and written for the lender, not for you. It will not report on damp, roof condition or movement in the way a survey does. If you want to understand the property's condition, you need your own survey.
When should I book the survey?
Book it after your offer has been accepted but before you exchange contracts. That window is the one point where you have a price agreed and still have room to renegotiate or withdraw if the survey finds something significant. Starting a few days after your offer is accepted avoids a last-minute rush.
Should I use the surveyor the estate agent recommends?
You can, but the choice is yours and you should check the firm independently. The agent acts for the seller, not for you. There is nothing wrong with a recommendation, but confirm the firm is RICS-regulated and book directly so the report is written for you. Our guide on how to choose the right firm sets out what to look for.
More on rics home surveys
Do I Need a House Buying Survey?
A RICS surveyor explains whether you need a house buying survey, why a mortgage valuation is not enough, and how to choose between Level 2 and Level 3.
Read →The Legal Process of Buying a House: A Plain-English Guide
A plain-English guide to the legal process of buying a house, including buying and selling at once, choosing a solicitor, and new build pitfalls.
Read →Risks of Buying a House Without a Survey
Buying without a survey might seem like a way to save money, but it can leave you exposed to significant costs and problems you had no way of seeing coming.
Read →Need a survey on a specific property?
Tell us the address and we will send a fixed price in writing, with no obligation.
Get your fixed quote →